Almost every buyer client of mine I spoke to this fall has asked me the same thing. Should we wait for the rates to come down?
Interest rates have gone up most of this year, and nobody wants to buy right before they drop. I understand why, but waiting can cost money too, mostly in equity you could have been building.
Here are real numbers. Say you buy a $750,000 home today with 20% down at 7.24%. Your payment is about $4,089 a month. In the first year, you pay down about $5,800 of the loan. If the home goes up even 3%, that's another $22,500, for close to $28,000 in equity.
Now say you wait a year. Chicago prices went up 8.3% last year. If that happens again, the same home costs about $812,000. Even if rates drop a full point, your payment on the new price would be about $4,000, only $90 less than if you had bought today. Meanwhile, the house gained $62,000, and that $62,000 went to whoever bought it.
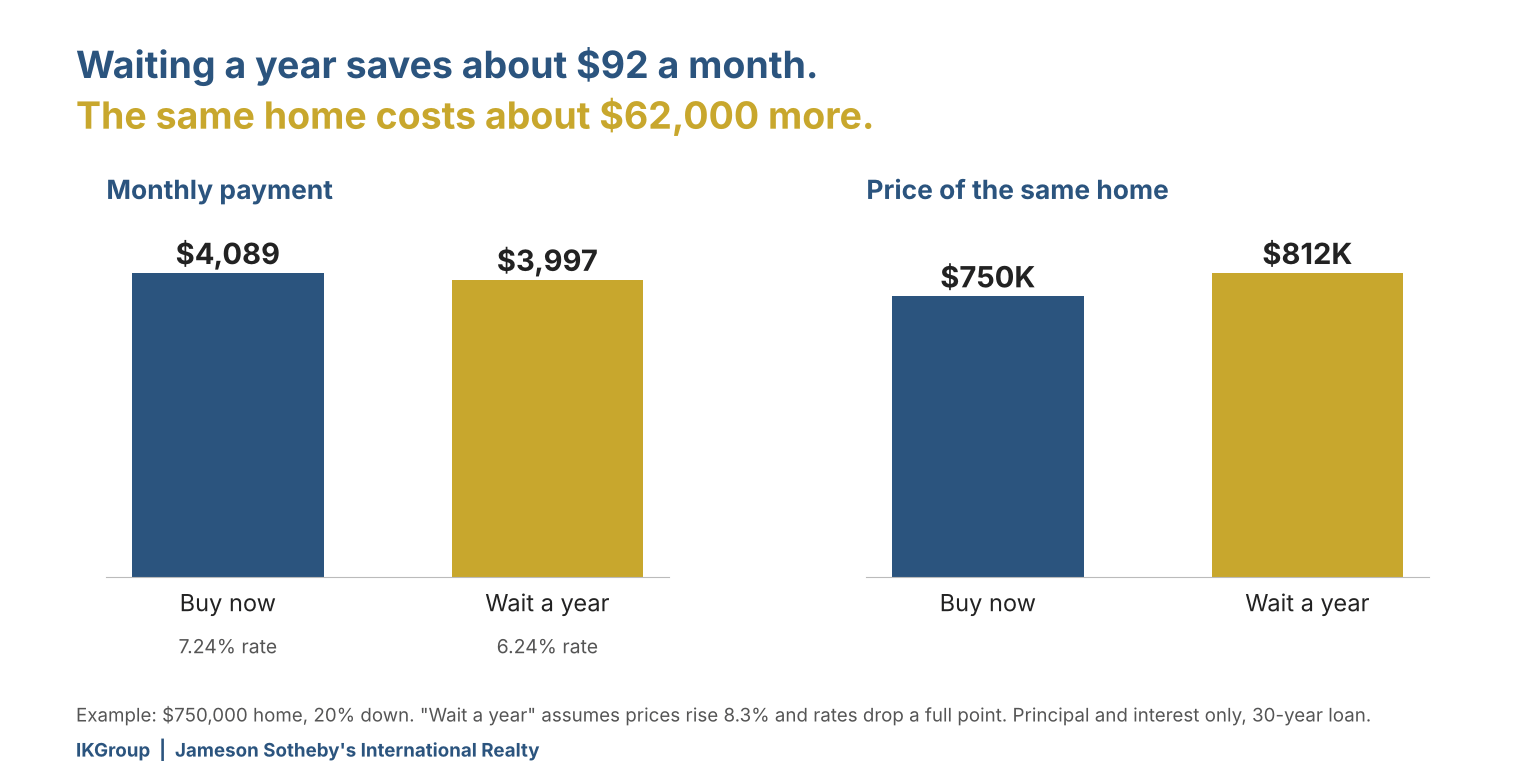
Payments shown are principal and interest only, on a 30-year loan.
Rent is the other cost of waiting. If you pay $3,500 a month, that's $42,000 over the year, and you don't see any of it again. Most renters I talk to know this, but it's easy to forget when you're focused on the rate. With a mortgage, at least part of each payment builds equity.
I've been selling homes in Chicago for 37 years, and when I started, rates were around 10%. People still bought, because they needed a home and the house was worth it. Today's rate is about 7.2%. That feels high after the 3% loans of a few years ago, but those were a short exception. Over the past 50 years, the average has been a little under 8%. Unlike the price, a rate can be changed later. If rates drop after you buy, you can talk to your lender about refinancing.
You can also lower your rate when you buy with a buydown. The seller pays an upfront fee to the lender, and in return you get a lower rate, either for the whole loan or just for the first year or two. That can bring your monthly payment down quite a bit. It doesn't work everywhere, though. In many Chicago neighborhoods, good homes still get more than one offer, and asking the seller to pay for your rate can make your offer look weaker. It does work on homes that have been on the market for a while, on new construction when the builder wants to close, or when a seller is already thinking about lowering the price. Your lender and I can tell you if it makes sense for the home you want.
This doesn’t mean everyone should buy right now. Waiting can be the right call if you're still saving for a down payment or aren't sure your job is stable. I've worked with three lenders for years, and I'm happy to connect you with one of them. They'll look at your numbers and tell you exactly what to fix, whether that's your credit score or how much more you need to save. Some of my buyers have done this a year ahead, and when the right home came along, they were ready.
If you own a home and are thinking about selling, this is also why buyers are still out there. Many of the buyers out there right now have run these same numbers.
If you've been holding off, fall is a good time to start looking again. Sellers this time of year usually have a reason to move, and they tend to be more willing to negotiate. Send me the homes you've been watching, and I'll show you what buying now would cost compared with waiting a year. One of my lenders can work out the rate side. Call or text me at 773.865.5661.
The numbers in this post are examples to show how the math works, not a loan offer. Your rate and payment will depend on your situation, so talk to a lender before you decide.